Portfolios
Every position, priced and measured.
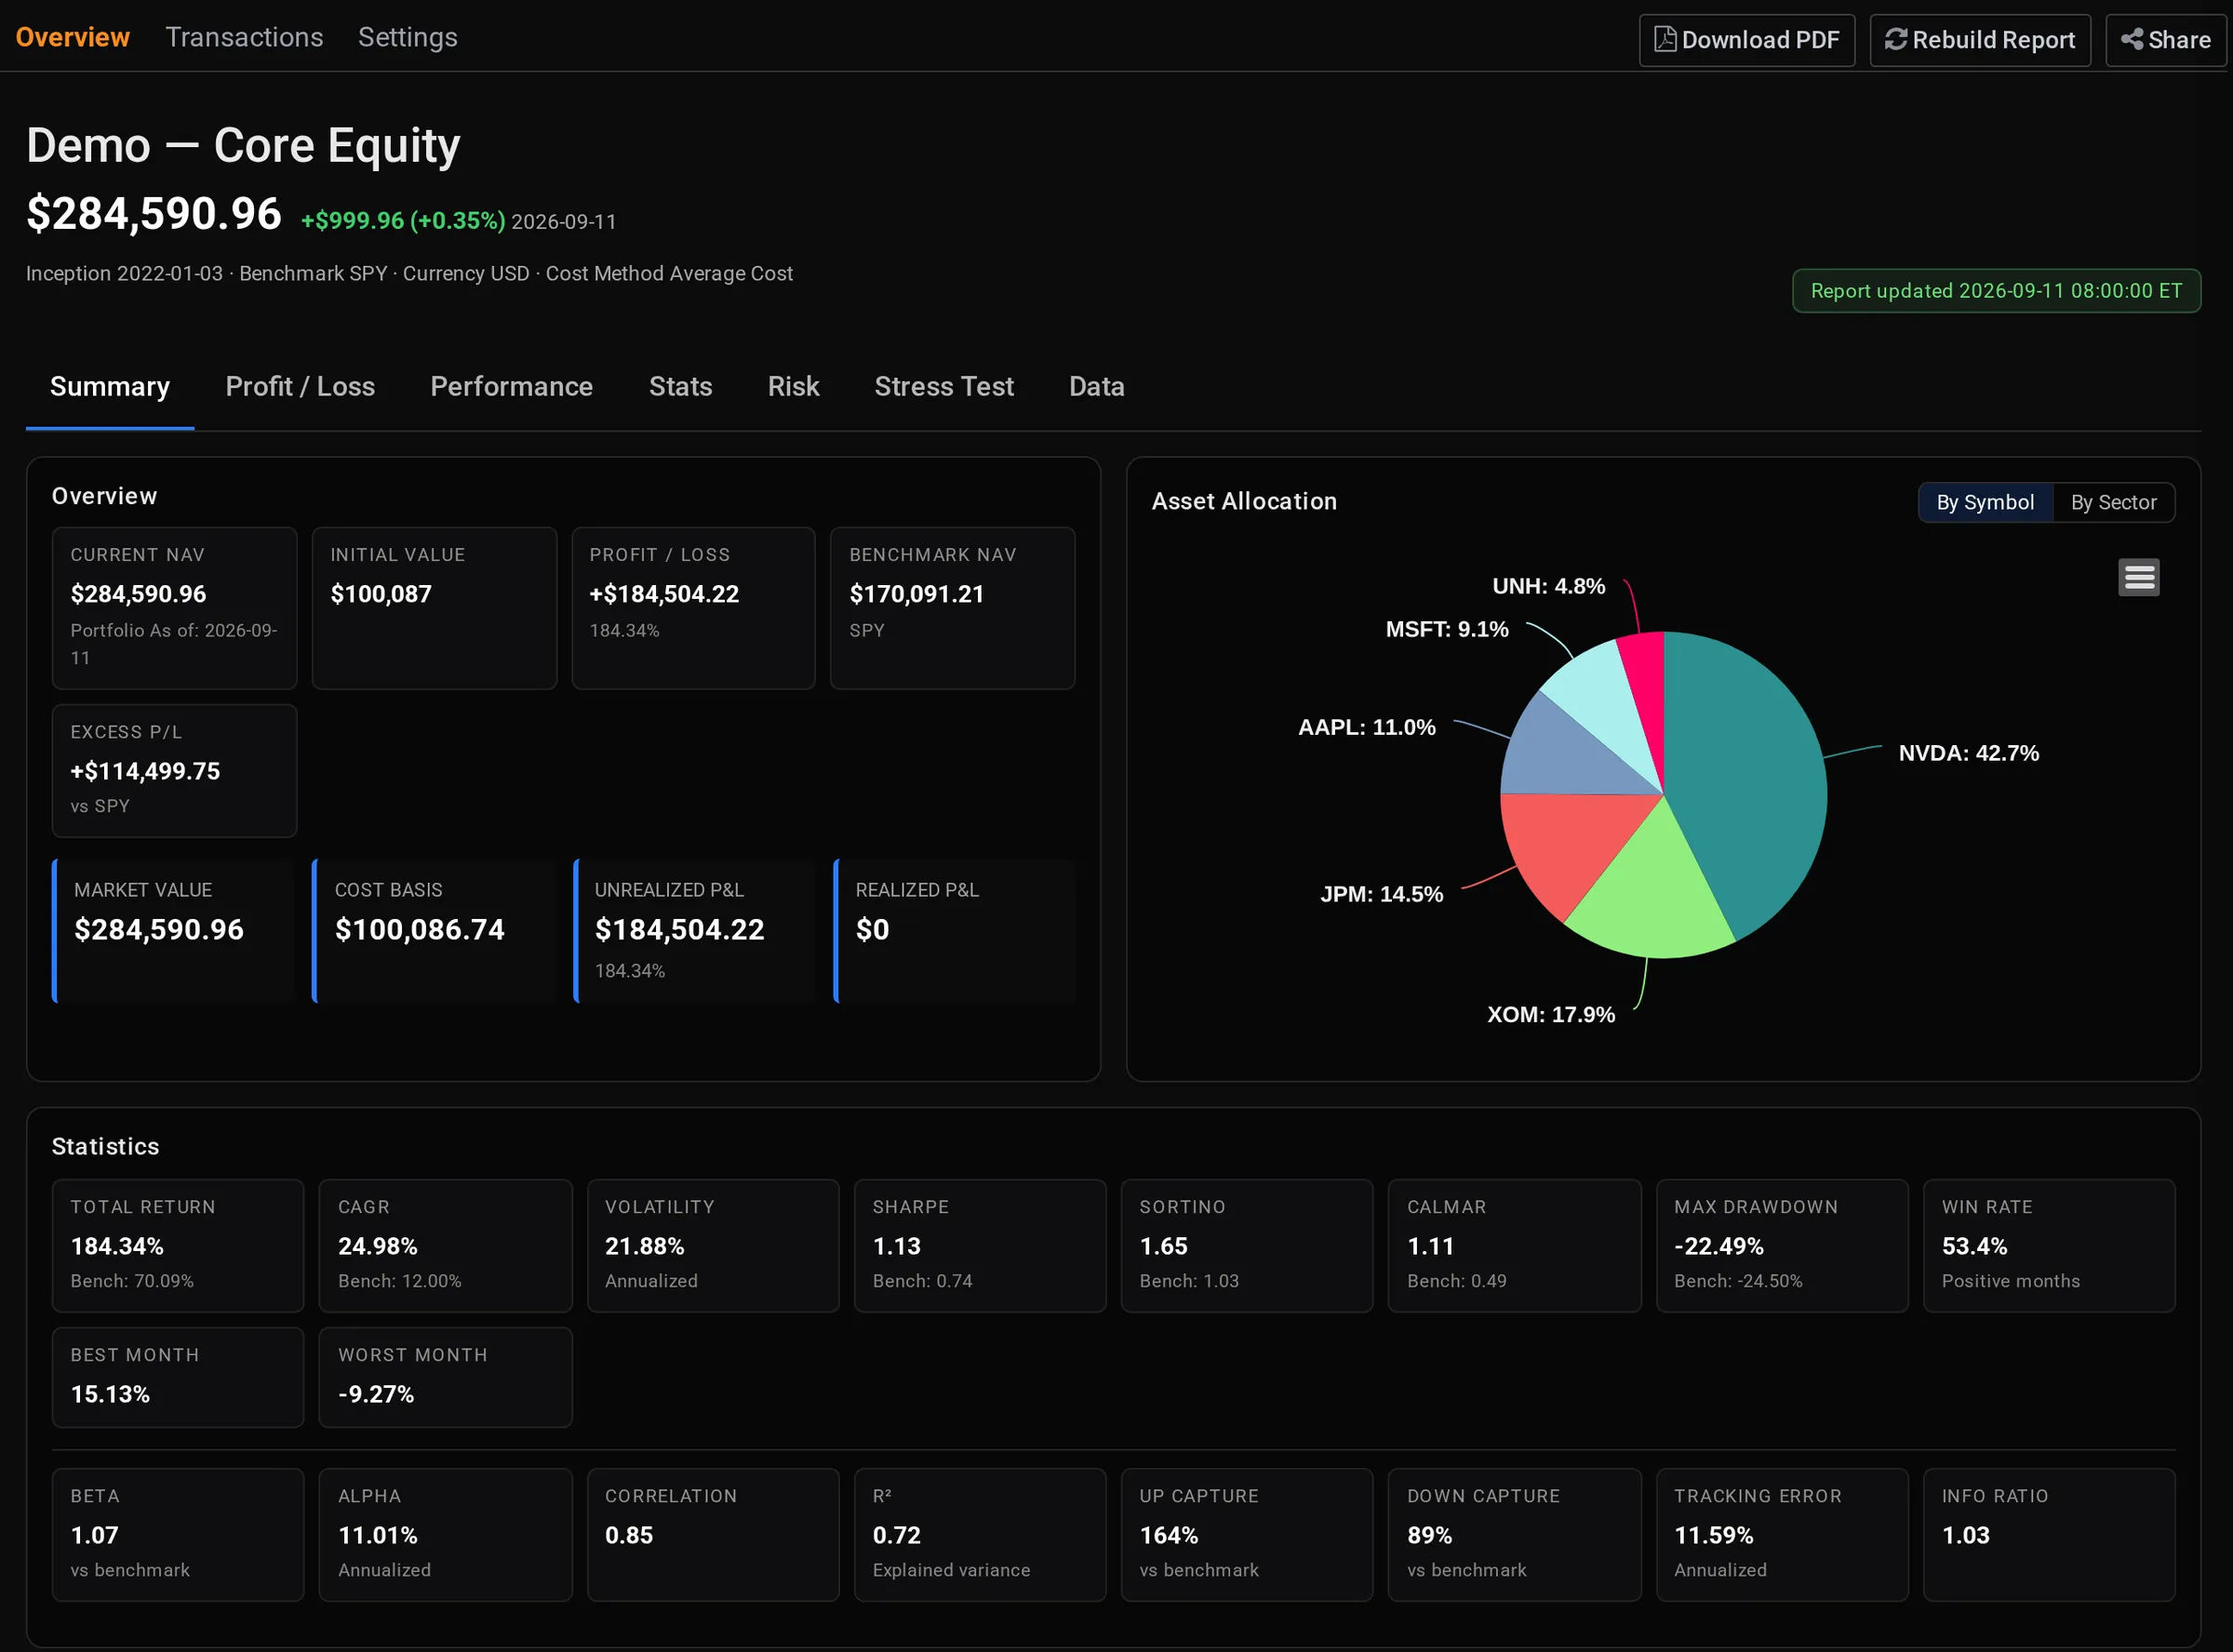
Enter your buys and sells. Holdings, performance and risk are worked out for you and kept up to date.
Free accounts can build portfolios and log transactions; the performance and risk figures need a paid plan.
-
Transactions in, holdings out
Log buys and sells with price, commission and date. Cost basis follows your choice of FIFO, LIFO or average.
-
Measured against your benchmark
Value over time, drawdowns, monthly and annual returns, trailing periods and up and down capture.
-
Risk and stress tests
Volatility, beta and risk-adjusted returns, plus stress scenarios run over your actual positions.
-
Split across accounts
Keep broker accounts apart inside one portfolio, and still see the whole thing together.
-
Compare against anything
Overlay any symbol on your portfolio to see how it would have tracked.
-
Share with your team
Give colleagues a read-only view of a portfolio.
Build your first portfolio.
Ask the market a question. Get a calculated answer.
The AI is not a chatbot bolted onto a document store. It calls the same analytics engine that powers every screen on this platform — so what comes back is a number it computed from raw history, with the command that produced it.
86,000+ instruments
Global equities, ETFs, funds, options, FX, commodities, crypto, economics, filings, transcripts and news — one normalised symbol universe with adjusted history.
A real analytics engine
Screening, backtesting, technicals, options analytics, correlations, seasonality and factor models — computed on demand from raw prices, never a stale cache.
It shows its working
Answers arrive with the charts, tables and tool calls behind them, so you can check the number instead of trusting a paraphrase.
Your own documents
Upload filings, decks and research. Ask across them and the answer cites the page it came from.
Agents and workflows
Multi-step research that runs the platform's tools for you — screen, pull the history, compute, compare, then write it up.
MCP, CLI and API
The same command catalogue from Claude, your own agent, a shell or your pipeline. The answer on screen is the answer your job gets at 4am.
You ask
“How does NVDA usually trade through earnings?”
It calls
→ ka.options_expected_move(NVDA)
It answers
NVDA has averaged a 9.2% absolute move on the day after earnings and closed higher 67% of the time. Two in three reactions land between −4.2% and +16.3% — the distribution is skewed right, not symmetric.
Every figure computed live from our own history — not scraped, not summarised.
Or start with