What's New
Product updates, improvements and fixes across the KlickAnalytics platform.
Launching Quant Tools: Close-to-Close Volatility Estimation
🚀 Introducing Quant Tools in KlickAnalytics
We’re excited to announce the launch of a new category in KlickAnalytics — Quant Tools. These are designed to give quants, traders, investors, and analysts deeper insights into market behavior using advanced quantitative techniques.
The very first tool we’re rolling out is the Close-to-Close Volatility Estimation (C2C Vol), which allows you to measure and analyze annualized volatility directly from daily price movements for any global instruments in KlickAnalytics.
This feature provides not only volatility series and historical stats, but also percentile ranks, spikes, and regime classifications to help you understand market risk and positioning like never before.
This is just the beginning — more Quant Tools are coming soon to expand your analytical edge. Stay tuned!
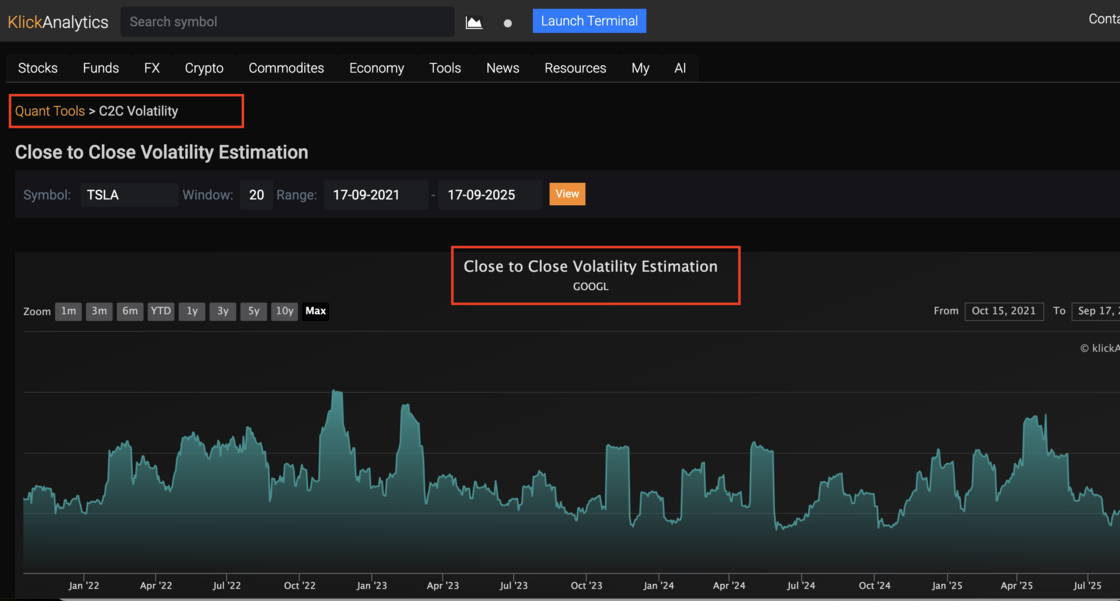
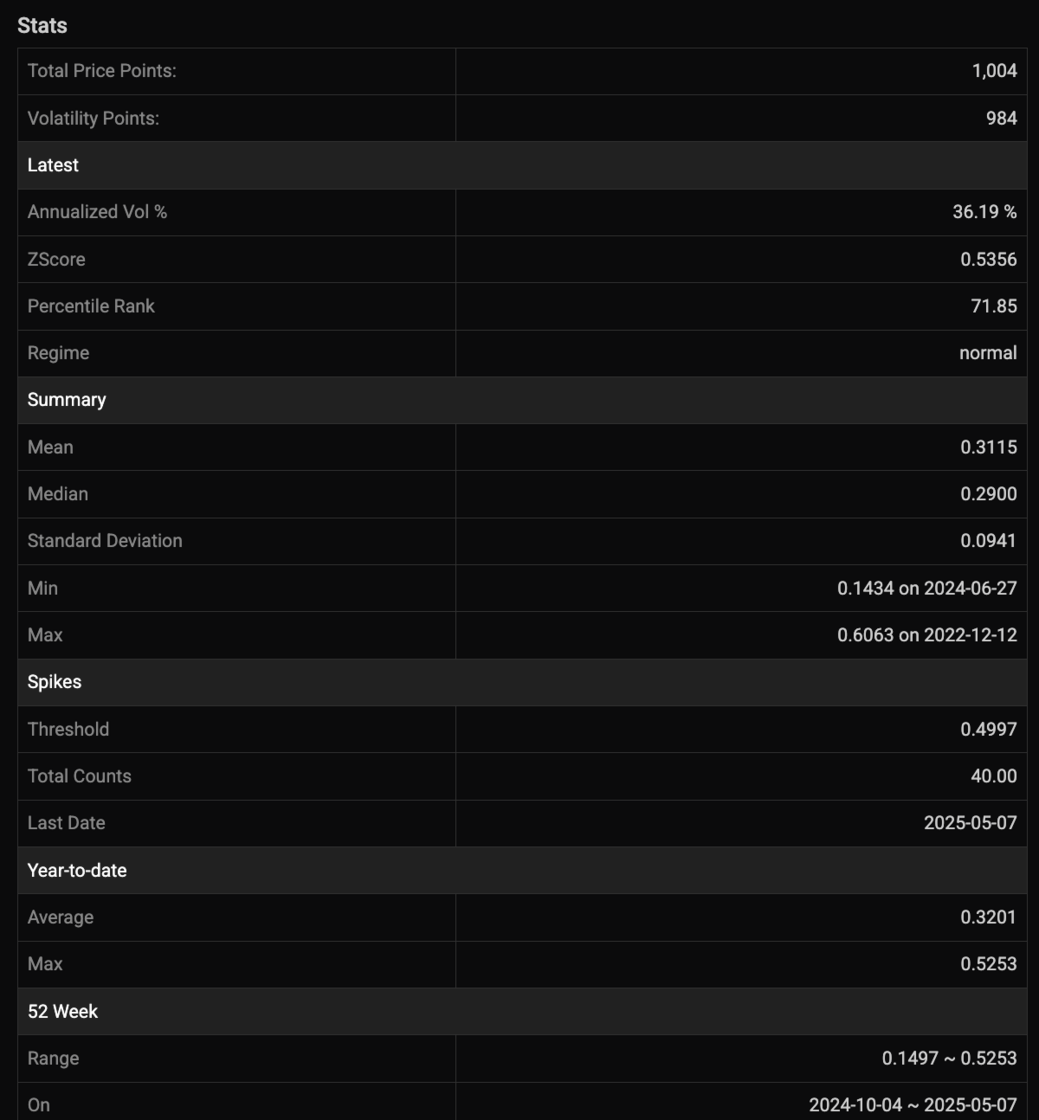
To access: From the top bar > Tools > Quant Tools > Close to Close Volatility Estimation
Ask the market a question. Get a calculated answer.
The AI is not a chatbot bolted onto a document store. It calls the same analytics engine that powers every screen on this platform — so what comes back is a number it computed from raw history, with the command that produced it.
86,000+ instruments
Global equities, ETFs, funds, options, FX, commodities, crypto, economics, filings, transcripts and news — one normalised symbol universe with adjusted history.
A real analytics engine
Screening, backtesting, technicals, options analytics, correlations, seasonality and factor models — computed on demand from raw prices, never a stale cache.
It shows its working
Answers arrive with the charts, tables and tool calls behind them, so you can check the number instead of trusting a paraphrase.
Your own documents
Upload filings, decks and research. Ask across them and the answer cites the page it came from.
Agents and workflows
Multi-step research that runs the platform's tools for you — screen, pull the history, compute, compare, then write it up.
MCP, CLI and API
The same command catalogue from Claude, your own agent, a shell or your pipeline. The answer on screen is the answer your job gets at 4am.
You ask
“How does NVDA usually trade through earnings?”
It calls
→ ka.options_expected_move(NVDA)
It answers
NVDA has averaged a 9.2% absolute move on the day after earnings and closed higher 67% of the time. Two in three reactions land between −4.2% and +16.3% — the distribution is skewed right, not symmetric.
Every figure computed live from our own history — not scraped, not summarised.
Or start with