What's New
Product updates, improvements and fixes across the KlickAnalytics platform.
Linear Regression via Machine Learning
To leverage the advancements in machine learning and more, we've added a new module to calculate the Linear Regression via machine learning. The new app 'Linear Regression'. The app will use the machine learning i.e.
The user will be able to select any global instrument e.g. Stocks, ETFS, Funds, Index, Commodities, Currency, Crypto
Set the duration of dates
The app will then take daily historical returns for the said symbol
Calculate the daily LAG1 returns i.e. Return of 1-Day before for each day
Run machine learning model to predict returns on above data set
Calculate the linear regression model by apply the fit for
Daily LAG1 return
Daily return
Calculate the linear regression line
Calculate the predicted returns based on the linear model
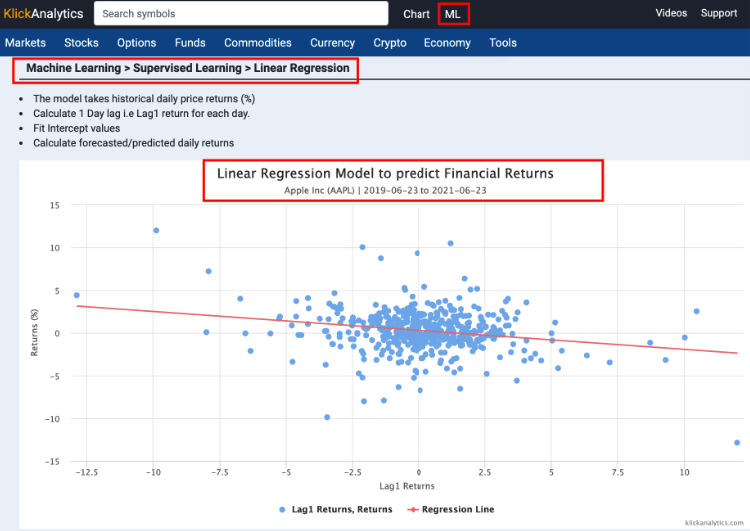
Provide a scatter plot to visualize the daily LAG1 returns, returns and regression line
The time series chart also provide a way to view the returns vs predicted returns and to see how many times the predicted returns direction was correct i.e. If the predicted returns and daily returns directions are same, it is considered a good forecasted direction.
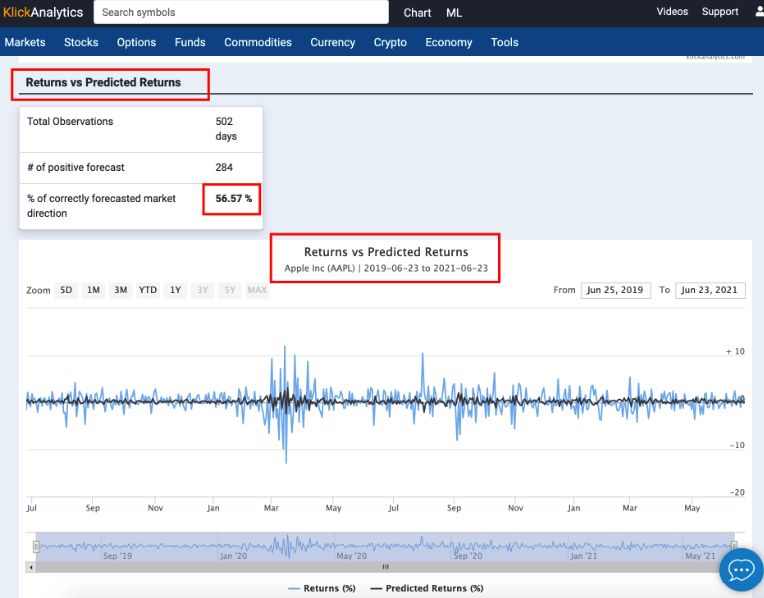
Also it provides stats like;
number of observations i.e Number of trading days,
of positive forecast
% of positive forecasted returns within the model
This is the very first Machine Learning model among the many more models to come at KlickAnalytics.com
To access: From the top bar, Click ML > Linear Regression
Ask the market a question. Get a calculated answer.
The AI is not a chatbot bolted onto a document store. It calls the same analytics engine that powers every screen on this platform — so what comes back is a number it computed from raw history, with the command that produced it.
86,000+ instruments
Global equities, ETFs, funds, options, FX, commodities, crypto, economics, filings, transcripts and news — one normalised symbol universe with adjusted history.
A real analytics engine
Screening, backtesting, technicals, options analytics, correlations, seasonality and factor models — computed on demand from raw prices, never a stale cache.
It shows its working
Answers arrive with the charts, tables and tool calls behind them, so you can check the number instead of trusting a paraphrase.
Your own documents
Upload filings, decks and research. Ask across them and the answer cites the page it came from.
Agents and workflows
Multi-step research that runs the platform's tools for you — screen, pull the history, compute, compare, then write it up.
MCP, CLI and API
The same command catalogue from Claude, your own agent, a shell or your pipeline. The answer on screen is the answer your job gets at 4am.
You ask
“How does NVDA usually trade through earnings?”
It calls
→ ka.options_expected_move(NVDA)
It answers
NVDA has averaged a 9.2% absolute move on the day after earnings and closed higher 67% of the time. Two in three reactions land between −4.2% and +16.3% — the distribution is skewed right, not symmetric.
Every figure computed live from our own history — not scraped, not summarised.
Or start with