What's New
Product updates, improvements and fixes across the KlickAnalytics platform.
New Quant Tool: Black-Scholes Options Calculator
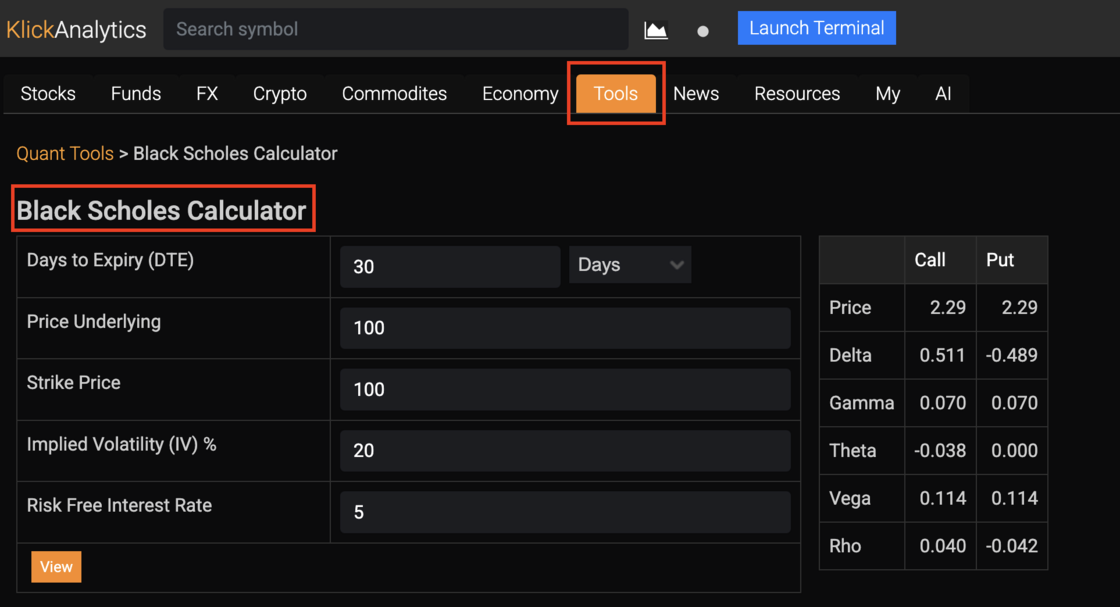
Now Price options and see Greeks in seconds with another quant tool at your finger tips.
Why it matters
- Instant, reliable pricing for quick sanity checks and “what-if” scenarios.
- Snapshot risk at a glance to choose strikes, hedges, and expiries faster.
Features
- Call & Put pricing with DTE in days or years
- Full Greeks: Delta, Gamma, Theta, Vega, Rho
- Inputs for Implied Volatility, Risk-Free Rate, and Dividend Yield
- Handy presets (7/30/90/365 DTE) plus custom values
- Clean, copy-friendly results in a dark-mode table
Perfect for
- Rapid pre-trade checks, education, and comparative strike selection.
To access: From the top menu > Tools > Quant Tools > Black-Scholes Calculator
Ask the market a question. Get a calculated answer.
The AI is not a chatbot bolted onto a document store. It calls the same analytics engine that powers every screen on this platform — so what comes back is a number it computed from raw history, with the command that produced it.
86,000+ instruments
Global equities, ETFs, funds, options, FX, commodities, crypto, economics, filings, transcripts and news — one normalised symbol universe with adjusted history.
A real analytics engine
Screening, backtesting, technicals, options analytics, correlations, seasonality and factor models — computed on demand from raw prices, never a stale cache.
It shows its working
Answers arrive with the charts, tables and tool calls behind them, so you can check the number instead of trusting a paraphrase.
Your own documents
Upload filings, decks and research. Ask across them and the answer cites the page it came from.
Agents and workflows
Multi-step research that runs the platform's tools for you — screen, pull the history, compute, compare, then write it up.
MCP, CLI and API
The same command catalogue from Claude, your own agent, a shell or your pipeline. The answer on screen is the answer your job gets at 4am.
You ask
“How does NVDA usually trade through earnings?”
It calls
→ ka.options_expected_move(NVDA)
It answers
NVDA has averaged a 9.2% absolute move on the day after earnings and closed higher 67% of the time. Two in three reactions land between −4.2% and +16.3% — the distribution is skewed right, not symmetric.
Every figure computed live from our own history — not scraped, not summarised.
Or start with