What's New
Product updates, improvements and fixes across the KlickAnalytics platform.
See the Expected Move Before Earnings
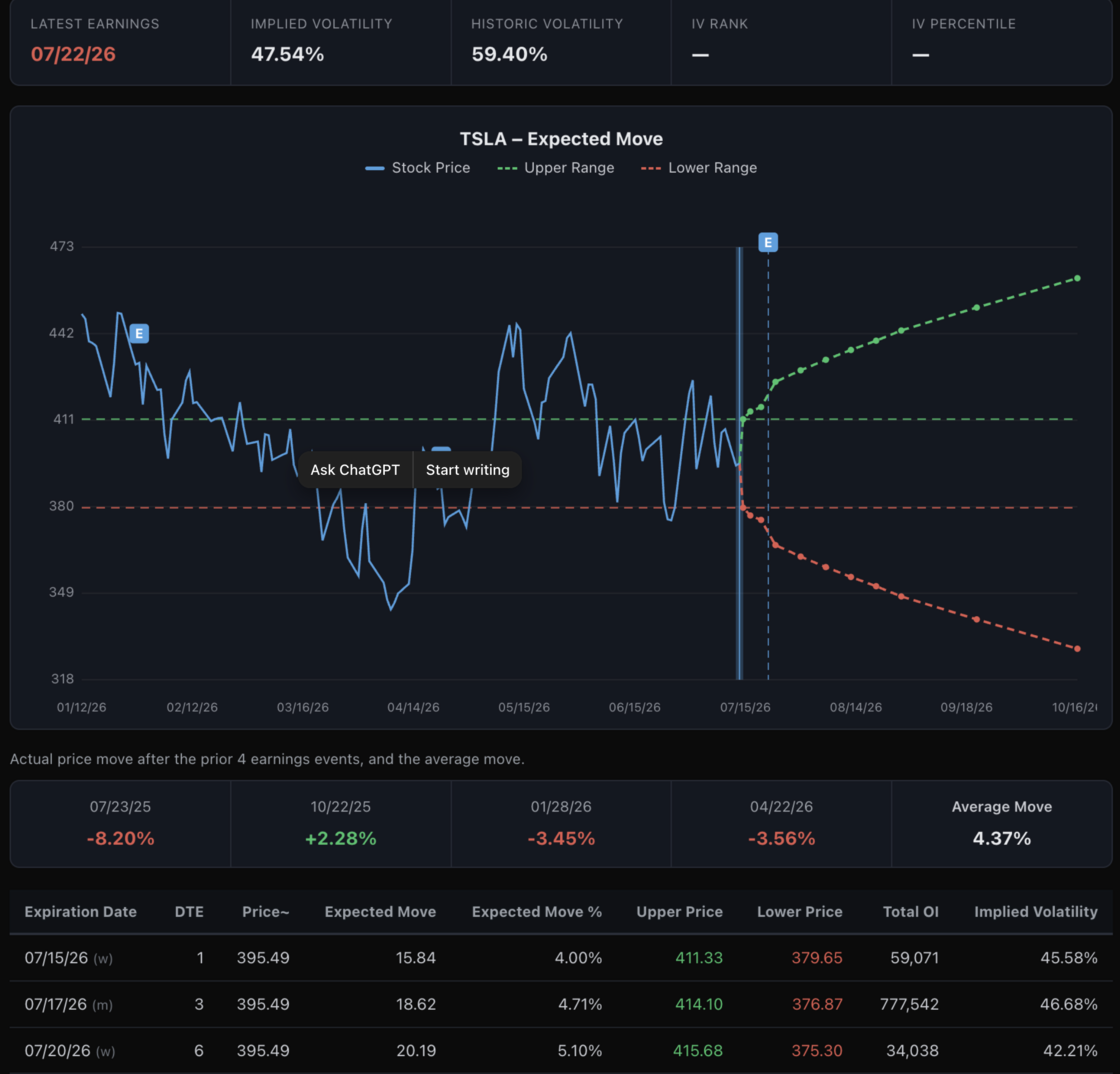
KlickAnalytics now gives you a dedicated Expected Move view for any symbol, helping you quickly understand how the options market is pricing upcoming volatility.
Track key data such as latest earnings date, implied volatility, historic volatility, IV Rank, IV Percentile, expected move amount, expected move %, upper and lower price ranges, days to expiration, open interest, and implied volatility by expiration—all in one place.
You can also view the projected move visually on the chart, compare it with the actual price moves from prior earnings events, and see the average historical move to better judge whether the current options market is pricing a bigger or smaller reaction than usual.
It’s a fast, practical way to analyze earnings risk, volatility expectations, and potential trading ranges before the event.
To view: search for any symbol say TSLA, and then click on Analysis > Options > Expected move
Ask the market a question. Get a calculated answer.
The AI is not a chatbot bolted onto a document store. It calls the same analytics engine that powers every screen on this platform — so what comes back is a number it computed from raw history, with the command that produced it.
86,000+ instruments
Global equities, ETFs, funds, options, FX, commodities, crypto, economics, filings, transcripts and news — one normalised symbol universe with adjusted history.
A real analytics engine
Screening, backtesting, technicals, options analytics, correlations, seasonality and factor models — computed on demand from raw prices, never a stale cache.
It shows its working
Answers arrive with the charts, tables and tool calls behind them, so you can check the number instead of trusting a paraphrase.
Your own documents
Upload filings, decks and research. Ask across them and the answer cites the page it came from.
Agents and workflows
Multi-step research that runs the platform's tools for you — screen, pull the history, compute, compare, then write it up.
MCP, CLI and API
The same command catalogue from Claude, your own agent, a shell or your pipeline. The answer on screen is the answer your job gets at 4am.
You ask
“How does NVDA usually trade through earnings?”
It calls
→ ka.options_expected_move(NVDA)
It answers
NVDA has averaged a 9.2% absolute move on the day after earnings and closed higher 67% of the time. Two in three reactions land between −4.2% and +16.3% — the distribution is skewed right, not symmetric.
Every figure computed live from our own history — not scraped, not summarised.
Or start with